Robert Kiyosaki’s $1.2 Billion Debt: What Real Estate Investors Can Learn
Is debt a wealth-building tool or a financial risk? The answer depends on what you do with it.
Those evenings brought together aspiring investors, business owners and people who simply wanted to better understand how money works. There were plenty of laughs, some healthy competition and some surprisingly revealing conversations about assets, liabilities, cash flow and financial independence.
Now, nearly three decades after Rich Dad Poor Dad was published in 1997, Kiyosaki is making headlines over approximately $1.2 billion in reported debt.
But before we decide whether that’s brilliant investing or a financial disaster, there’s a much more important question worth asking.
When does borrowing money help build wealth, and when does it put everything you’ve built at risk?
Robert Kiyosaki’s $1.2 Billion Debt: There’s More to the Story
According to recent reporting, Kiyosaki has publicly discussed approximately $1.2 billion in debt associated with real estate investments.
His former wife and business partner, Kim Kiyosaki, clarified that the reported debt is associated with a group of real estate investors and their holdings, reportedly including approximately 1,500 apartment units. It does not represent $1.2 billion in personal borrowing by Robert Kiyosaki alone.
That distinction matters.
Debt secured against income-producing properties is very different from unsecured personal debt. Real estate investors regularly use financing to acquire properties, generate rental income and build equity.
But here’s where I would challenge the narrative.
Just because debt is backed by real estate doesn’t automatically make it good debt.
The real question is whether the underlying investment can support that debt, including when circumstances change.
Good Debt vs. Bad Debt in Real Estate Investing
One of the central lessons associated with Rich Dad Poor Dad is the idea that borrowing money to acquire income-producing assets can help create long-term wealth.
And there’s merit to that principle.
Real estate investors often use leverage, meaning borrowed funds, to purchase properties they might not otherwise be able to acquire outright.
For example, an investor purchasing a $700,000 rental property with a 20% down payment would finance approximately $560,000, before considering closing costs and other expenses.
If the property generates sufficient rental income to cover mortgage payments, property taxes, insurance, maintenance, vacancy allowances and other operating costs, it may contribute to the investor’s long-term financial goals.
But what happens if interest rates rise at renewal? What if the property sits vacant? What if major repairs become necessary or rental income doesn’t keep pace with expenses?
These are not unusual circumstances. They’re part of owning investment real estate.
Leverage can magnify returns, but it can also magnify losses.
That’s why responsible real estate investing requires more than identifying a property with potential appreciation.
It requires understanding the numbers, the risks and the financial capacity to manage the investment over time.
What Our CASHFLOW Game Nights Taught Us About Investing 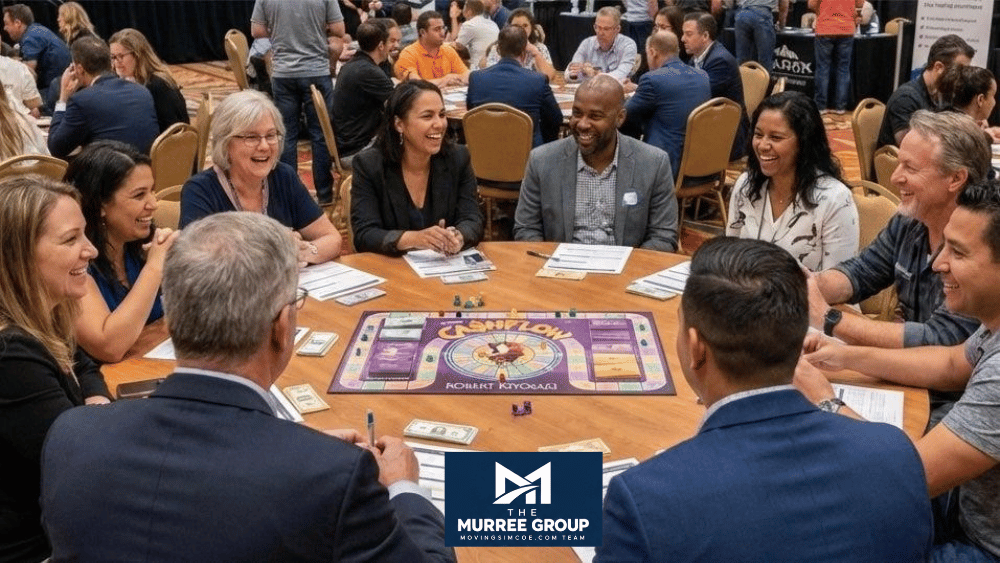
When we hosted CASHFLOW game nights as part of our investor-focused workshops, one of the most interesting things was watching how differently people approached the same financial decisions.
Some participants were eager to acquire assets quickly. Others were cautious about taking on debt. Some focused on immediate cash flow, while others looked at long-term opportunities.
And sometimes, the decisions that seemed smartest at the beginning of the game didn’t produce the results people expected.
That was part of the learning experience.
The game encouraged participants to think about how income, expenses, assets, liabilities and borrowing decisions affect financial independence.
More importantly, it created an environment where people could ask questions, challenge assumptions and learn without putting their actual savings or financial security at risk.
I’ve always believed financial literacy should be accessible, practical and part of everyday conversations.
Particularly for women, families, entrepreneurs and individuals navigating significant life transitions, understanding financial decisions can be an important part of building independence and creating more choices.
Financial literacy isn’t simply about becoming wealthy. It’s about understanding your options and having the confidence to make informed decisions.
What Does This Mean for Real Estate Investors in Barrie and Simcoe County?
Whether you’re considering a rental property in Barrie, a duplex in Orillia, an investment property in Innisfil or a commercial real estate opportunity elsewhere in Simcoe County, the same fundamental principles apply.
But every investment needs to be evaluated on its own merits.
Local rental demand, purchase price, property condition, permitted uses, municipal regulations, financing terms and operating expenses all influence whether a property makes financial sense.
Investors also need to distinguish between cash flow and appreciation.
A property may increase in value over time, but appreciation is not guaranteed. Likewise, rental income may offset ownership expenses without necessarily producing positive monthly cash flow.
Refinancing to access equity may create additional investment opportunities, but it can also increase debt obligations and financial exposure.
For anyone considering real estate investing in Barrie or the surrounding Simcoe County communities, asking the right questions before purchasing is essential.
The goal shouldn’t be to borrow as much as possible. It should be to understand whether the investment supports your financial position, risk tolerance and long-term objectives.
Financial Literacy Still Matters, Perhaps More Than Ever
I don’t believe every principle presented in Rich Dad Poor Dad should be accepted without question, nor do I believe Kiyosaki’s approach to borrowing is appropriate for every investor.
But his work helped introduce financial concepts to millions of readers and encouraged people to think differently about money, assets and wealth creation.
And those conversations are still worth having.
We need more opportunities to discuss responsible investing, financial independence and long-term planning without the pressure of quick returns or promises of guaranteed success.
After more than two decades in real estate, I’ve learned that a successful decision isn’t measured solely by what someone acquires.
It’s measured by how well that decision supports their financial circumstances, priorities and future goals.
That’s the thinking behind our approach at The Murree Group | MovingSimcoe.com Team.
Clarity Before Commitment™.
Should We Bring Back CASHFLOW Game Nights in Barrie?
Reading about Kiyosaki’s latest headlines reminded me how valuable those evenings were, not simply for learning about real estate investing, but for bringing people together to exchange ideas and perspectives.
Perhaps it’s time to bring them back.
Have you ever played Robert Kiyosaki’s CASHFLOW game or read Rich Dad Poor Dad?
Do you believe debt is a useful tool for building wealth, or do investors sometimes underestimate the risks?
And here’s what I’d really love to know:
If we brought back our CASHFLOW game nights or hosted another real estate investor and financial literacy workshop in Barrie, would you be interested in joining us?
Share your thoughts in the comments or reach out to The Murree Group. We’d love to hear from those who attended our earlier workshops and anyone interested in joining the conversation for the first time.
Because sometimes the best investment you can make is in your own understanding.